CBS

Entrance of the Maal Microfinance L.T.D office with the Maal logo above the door

About us

A Somali institution built to close the financing gap

Established in 2020 and licensed by the Central Bank of Somalia, Maal Microfinance serves micro, small and medium enterprises, women entrepreneurs and young people who lack access to formal banking.

Overview

Why Maal exists

Maal Microfinance was established to address critical gaps in Somalia’s business sector, formal and informal, with a particular focus on MSMEs and the financial exclusion of women entrepreneurs.

It was founded in response to limited access to tailored financial services, the absence of collateral and asset ownership among women, lack of identification documents, credit assessment that relies heavily on collateral, and persistent poverty caused by inadequate financial inclusion and education.

An initial investment of $1.2 million from an angel investor and a key stakeholder funded the Mogadishu headquarters, licensing and registration, office infrastructure and the first management team. The institution has since grown to include a diverse, experienced board, while the original investors remain key stakeholders.
Founded in Mogadishu
2020
Initial capital investment
$1.2M
Districts reached
15
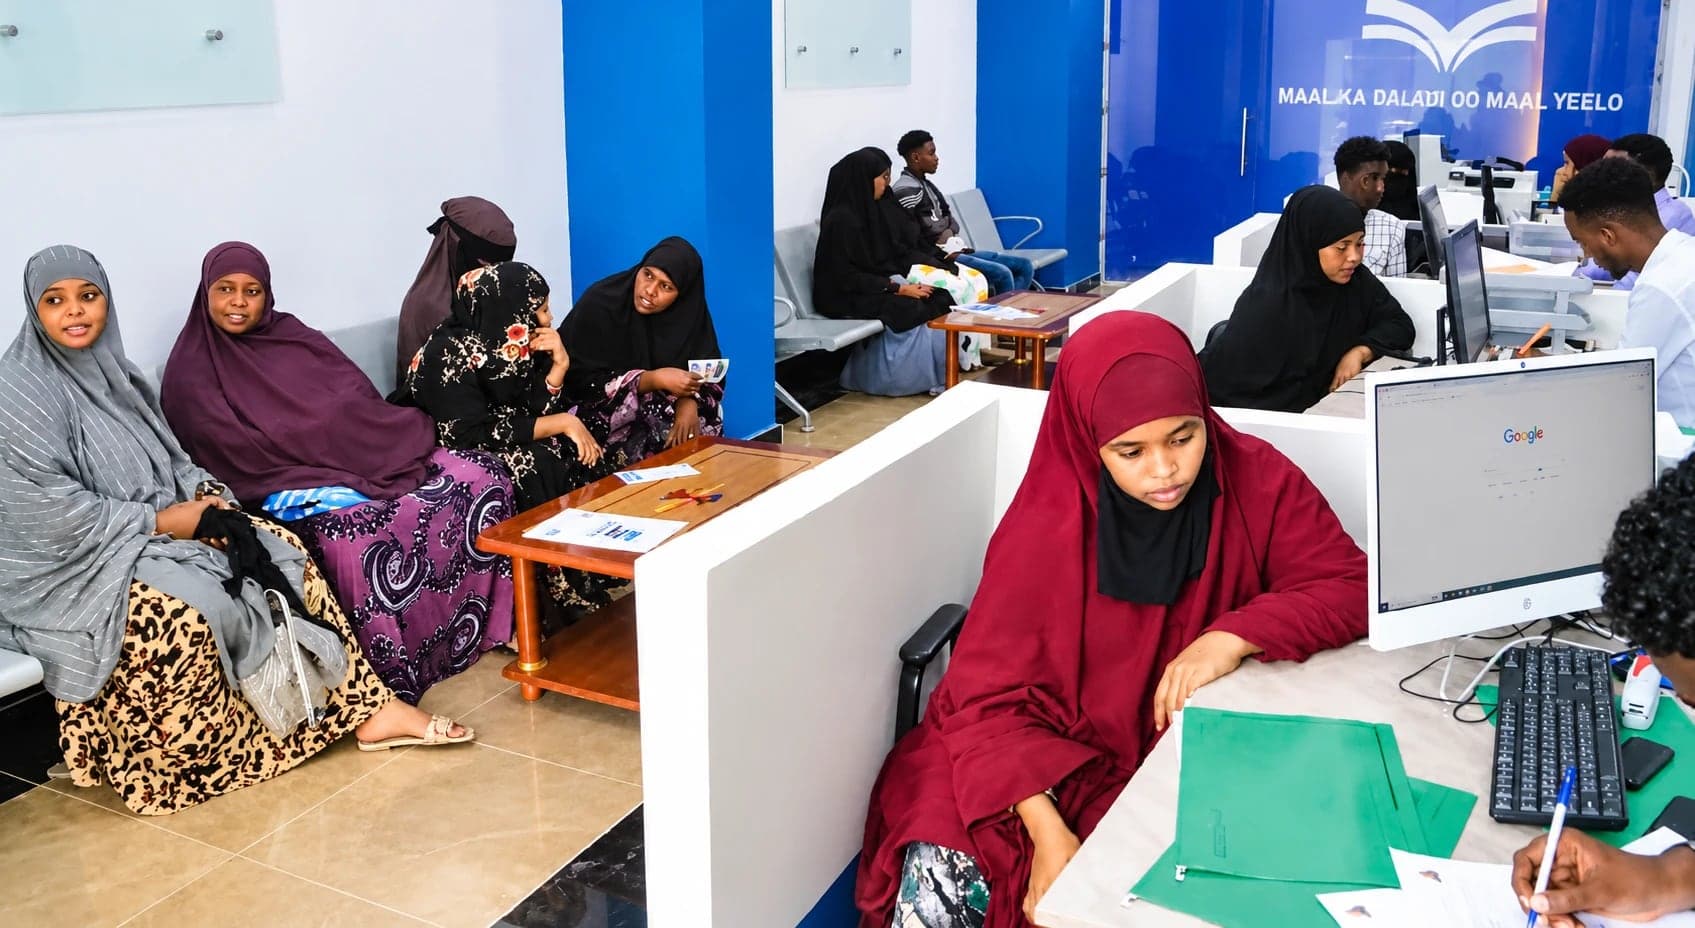
Customers wait in the Maal Microfinance branch while staff at service desks help clients
Entrance of the Maal Microfinance L.T.D office with the Maal logo above the door

Our purpose

What guides us

Our vision

To become a vibrant MFI that effectively supports financial inclusion and poverty eradication, and to provide an environment for easy access to financial services and products for businesses, MSMEs, youth, women and women in business — formal and informal — in Somalia.

Our mission

To facilitate and foster an enabling environment for sustainable, empowering, innovative and inclusive educational financial services and products for the poor, women, women in business, MSMEs and businesses, through a customer-based approach and participation.

Core values

  • Accountability & transparency
  • Equity, fairness & equalityIn how we treat members, customers, communities and stakeholders.
  • Microfinance best practice
  • Innovation & creativity
  • Non-discriminatory services
  • Good governance
  • Political independence
  • Environment-friendly enterprise

Growth

Five years of steady growth

Figures from the Maal Microfinance company profile.

Customers served
12,000+
Financing disbursed
$12.5M+
Districts reached across Somalia
15
Of beneficiaries are women and youth
90%
400+
Hectares of farmland financed
350+
Households provided with solar financing
20+
Fishing cooperatives financed
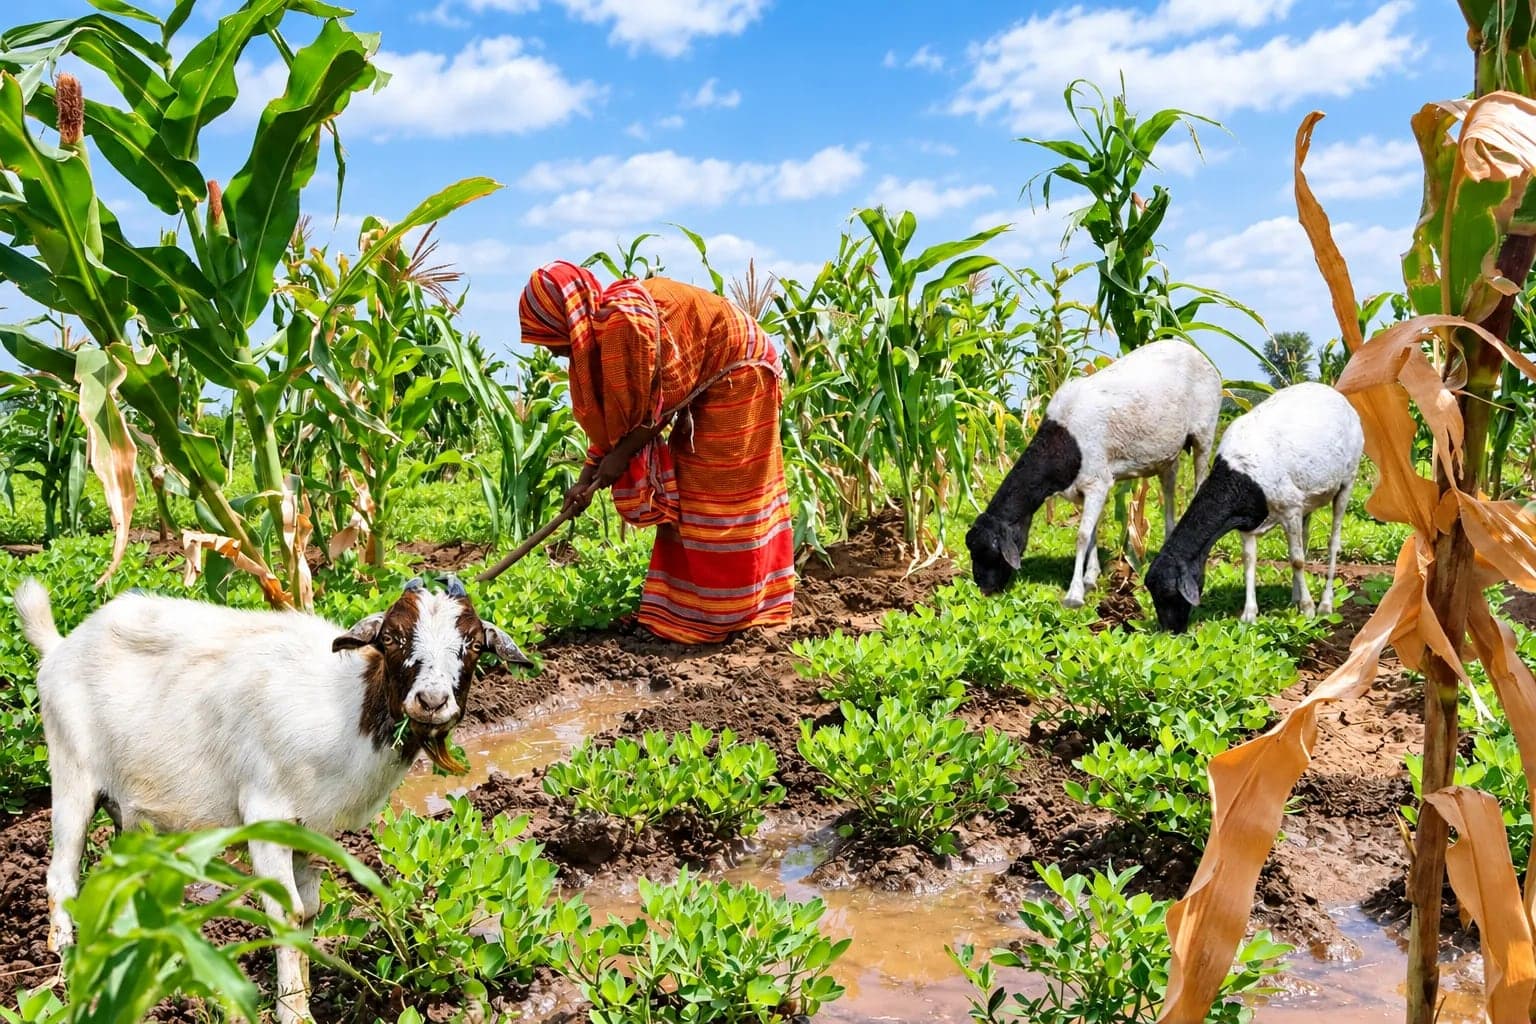
A farmer tends a field of maize and groundnuts in Afgooye while goats graze nearby

Islamic finance

Sharia-compliant by design

Our financial products are provided within the statutes of Sharia law, and its principles are applied to every product we offer. Our savings programmes follow the same principles.

  • Every product is structured within the principles of Sharia
  • Taran savings share investment profits through Mudaraba
  • A Sharia compliance committee of the board oversees our products

Strategic objectives

Traditional practice, modern finance

Maal integrates community-based practices with modern financial innovation to empower individuals and entrepreneurs through accessible financial services, education and microcredit.

  • 01

    Financial literacy

    Education on business models, financial management and business structuring.

  • 02

    Community-based savings

    Encouraging pooled resources, group savings and structured financial contributions.

  • 03

    Innovative lending

    Free accounts, collateral-free loans and credit profiling technologies.

  • 04

    Entrepreneurial support

    Helping start-ups and MSMEs with financial education and business development.

  • 05

    Sustainable growth

    Widening access to financial services for long-term economic empowerment.

Governance

How we are organised

Maal Microfinance has an assembly headed by a chairperson and a Board of Directors led by a revolving chairman. The management team is headed by a Chief Executive Officer accountable to the board.

  • Assembly & Board of Directors

    Strategic oversight, supported by an external auditor.

  • Board committees

    Sharia compliance; credit; human resources; and risk, compliance & audit.

  • Chief Executive Officer

    Leads management, with a chief internal auditor and a chief of risk & compliance.

  • Finance, credit & debt recovery

    Finance management and reconciliation, credit assessment and debt recovery.

  • Operations

    Dedicated Tooko, Taran and Taakulo managers and officers.

  • Support functions

    ICT, sales & marketing, HR & administration, housing & real estate, and compliance.

Mandate

Our mandate objectives

Derived from our articles of association, these objectives define how we serve our target customers.

Microfinance
Urban and rural lending, community-owned banking and asset development strategies.
Entrepreneurship
Small-business development, hands-on learning and technical know-how leading to self-employment, plus life-skills development.
Dynamic social network
Sharing resources, local and global interdependence, and mobilising social networks.
Community investment
Consumer-owned businesses, social businesses and social investment.
Organisation and governance
A good corporate governance structure that ensures sustainability and transparency, with a board of directors drawn locally and regionally.
Exchange of experiences
Sharing experiences, ideas, technologies and information to strengthen operations.
Conducive atmosphere
An environment of innovation and creativity through research and solution development.
Management and operations
An organisation that lowers operating costs while widening access through technology and an agency network.
Information technology
Software and mobile applications for customers and field agents, online account opening and credit analysis, and building credit histories for the unbanked.
Foster education
Financial education and training through the agency network and partnerships with NGOs in financial services.
Enhanced capacity
Capacity building for management and every department.
Resource mobilisation
Mobilising resources for the institution’s sustainability.

Work with us

Explore our products, or contact our team about partnerships and media enquiries.

Call2773
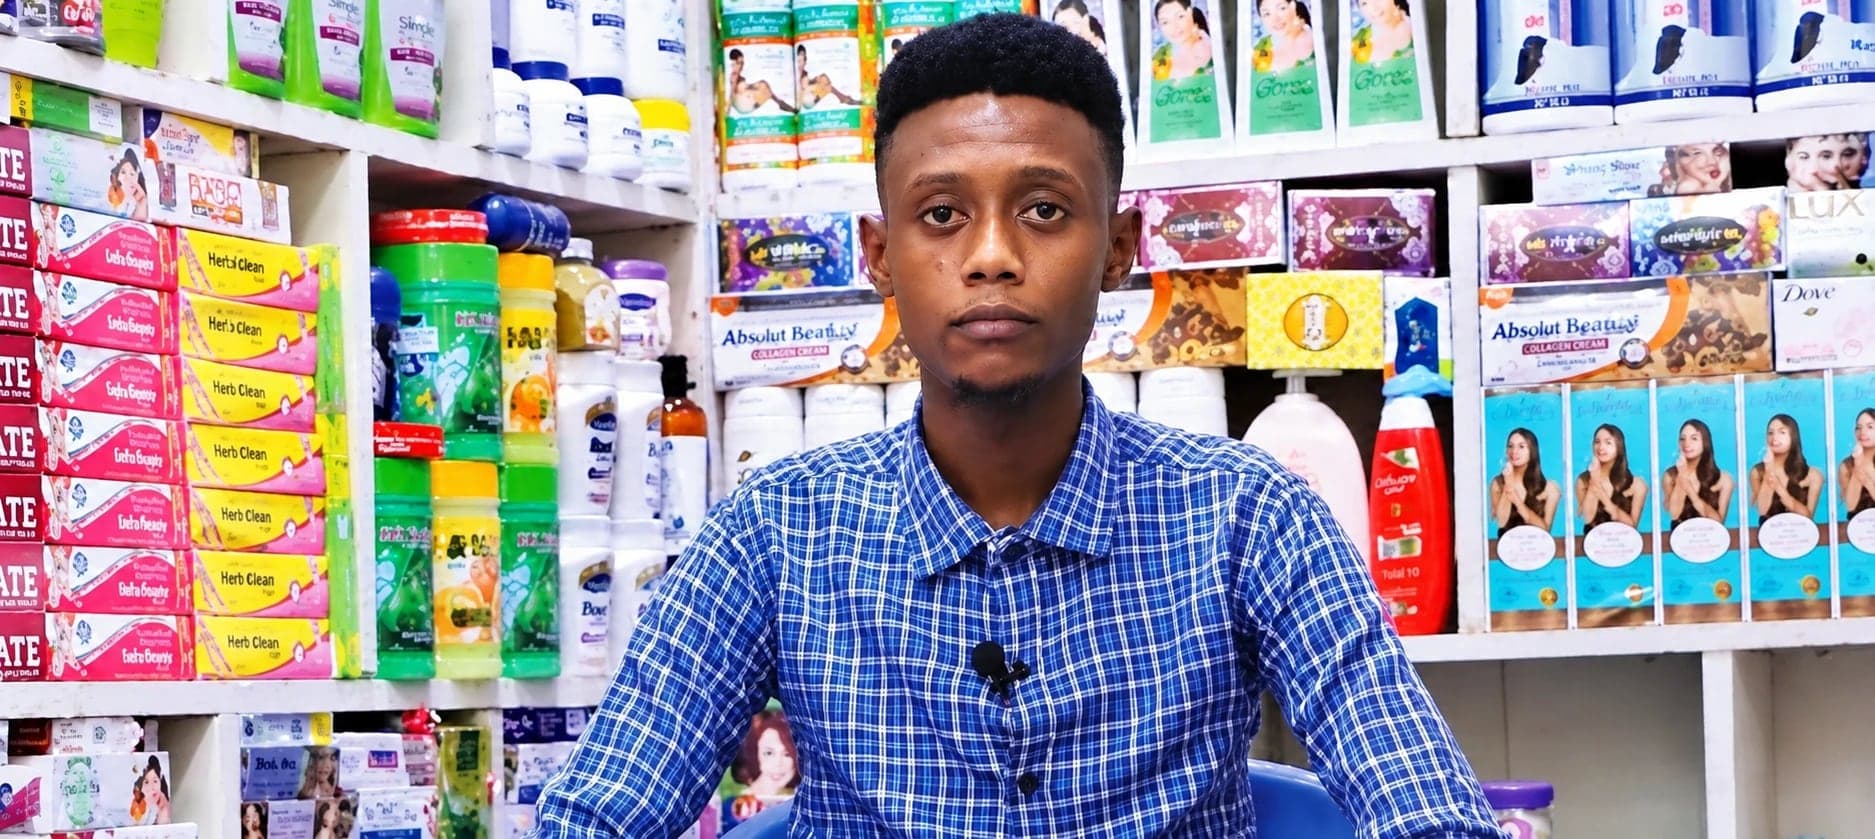
A young entrepreneur sits in his cosmetics shop